


Search "payday loans that accept Chime" and most of the ranking lists claim that "most" or "many" payday lenders work with Chime. Financer, SuperMoney, and BadCredit.org all publish some version of that claim without citing a single lender's own FAQ, and TheCreditPeople runs a general explainer on the same question with no primary-source lender citations at all. Several of those pages cite Plaid support as if it settles the question, treating "this lender uses Plaid" and "this lender accepts Chime" as the same fact. They aren't the same fact: even LendEDU doesn't separate "Chime works for funding" from "Chime works for repayment only," a distinction that turns out to matter for at least one lender in this review.
I went through the help pages and disclosures for six payday and installment lenders plus Chime's own site, and here's the honest answer: no lender in this review has a public statement that affirmatively confirms Chime acceptance by name. What's documented is narrower, and in some ways more useful, than what the roundup sites tell you.
Advance America explicitly excludes prepaid-type accounts. One lender's own blog spells out that Chime can be added only as a secondary payment method, never as the primary account for an application. Several more simply require "an active checking account" and never mention Chime, prepaid cards, or online-only banks at all. And before you shop for payday loans with Chime through a third party, Chime itself already sells three products that solve the same cash-flow gap for less.
Do Chime Payday Loans Exist?
Chime doesn't call anything a payday loan, and it shouldn't. What it offers are short-term advances tied to your direct deposit history, structured nothing like a two-week storefront loan with a flat fee per hundred dollars borrowed. This site's own review of no-overdraft checking accounts compares Chime against other no-overdraft accounts, which is useful background before you weigh Chime's own advances against what Advance America or Speedy Cash would charge you.
Chime's Cheaper First Stop: SpotMe, MyPay, and Instant Loans
Three Chime features cover the same emergency-cash need a payday loan targets. None of them require qualifying with an outside lender, and none of them charge anything close to payday-loan pricing.
SpotMe
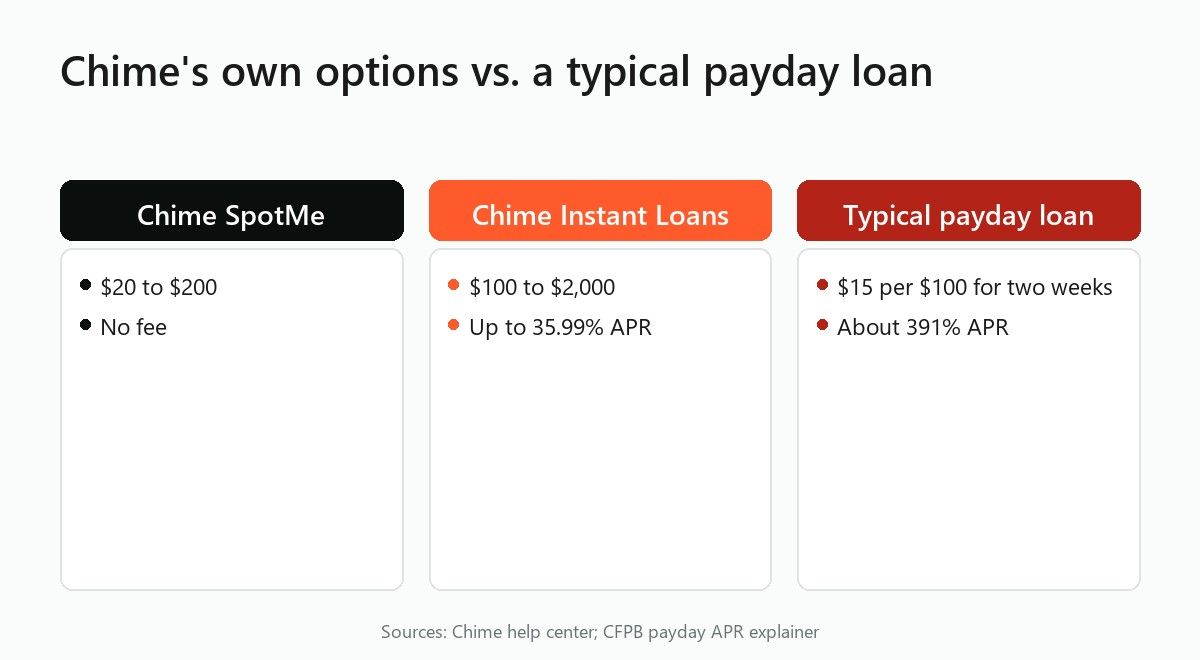
SpotMe is overdraft coverage, not a loan. Chime advances you $20 to $200 with no fee, as long as you've had a qualifying direct deposit of $200 or more within the last 34 days, per Chime's SpotMe help page.
MyPay
Chime's MyPay page states you can pull $20 to $500 per pay period, with up to $1,000 available for some members. The cost is an instant-transfer fee of 3%, with a $2 floor and a $5 cap, and Plaid linking to an outside account is optional rather than required. MyPay already appears in our roundup of lower-cost paycheck advances, where we compare it against other advance products.
Instant Loans
The newer Instant Loans product, launched in March 2025, is missing from most competitor articles on this keyword. Instant Loans range from $100 to $2,000 depending on eligibility, carry a maximum APR of 35.99%, and are issued by The Bancorp Bank N.A. and serviced by Chime Capital LLC, per Chime's Instant Loans help page.
To qualify, you need to be 18 or older, hold a Chime Checking Account in an eligible state, show a single qualifying deposit of $200 or more in the last 34 days, and have at least $400 in cumulative qualifying deposits each calendar month. Chime's own page states no late fees and no compounding interest, a structural difference from the flat per-hundred-dollar fee a storefront payday lender charges.
Even at the high end of that range, 35.99% APR is a fraction of what a typical storefront payday loan costs. The CFPB's payday-loan APR explainer documents the standard structure: roughly $15 per $100 borrowed over a two-week term, which annualizes to about 391% APR. That's the baseline every third-party lender in this comparison gets measured against.
Payday Loans That Accept Chime: The Lender-By-Lender Comparison
Here's what each lender's own bank-account language says: the Possible Finance restriction first, then Advance America's prepaid-card exclusion.
Possible Finance: Secondary use only, not primary
Possible Finance is the clearest documented case in this review. The lender's own blog states plainly that a Chime account can't be linked through Plaid to serve as the primary account for a loan application. Chime can be added only as a secondary or additional payment method, useful for paying down a balance you already owe but not for getting approved in the first place, according to Possible Finance's own blog. That's a meaningful distinction competitor articles gloss over: "Chime works with this lender" and "Chime works with this lender for repayment only" are two different claims, and only Possible Finance's own page draws the line between them.
Advance America: Excludes prepaid cards
Advance America's FAQ for online loans states that prepaid cards aren't accepted and that applicants need a checking account number along with an ABA routing number, per Advance America's own FAQ. This is a prepaid-card exclusion, not a Chime-specific rejection. Advance America's own FAQ does not name Chime.
Lenders With No Public Statement on Chime
Four lenders in this review publish no account-type statement that names Chime. Each of their own FAQs describes the funding mechanics a typical applicant needs, an active checking or savings account and a routing number, without naming Chime, prepaid accounts, or online-only banks specifically, so none of them get a compatibility claim here. This is the "we checked, they don't say" tier, and it deserves to be named rather than silently dropped from the comparison the way most roundups handle it.
- OppLoans. The lender's own bank-servicing page describes how payments move but doesn't list accepted or excluded account types. Could not verify Chime compatibility.
- NetCredit. NetCredit's FAQ requires an active checking account and doesn't mention Chime, prepaid accounts, or online banks. Could not verify Chime compatibility.
- MoneyKey. MoneyKey's FAQ asks for a checking or savings account and gives no account-type carve-out. Could not verify Chime compatibility.
- Speedy Cash. Speedy Cash's online-loan FAQ requires a checking account and doesn't address prepaid or online-only banks. Could not verify Chime compatibility.
If a page you're reading claims one of these four "accepts Chime," ask where that claim comes from. In this review, it doesn't come from the lender.
A missing statement about Chime doesn't mean rejection any more than it means approval. It means the only way to know for certain, for any of these four lenders, is to ask them directly before you apply.
Why Some Lenders Reject Online-Only Banks
Online lenders that fund and collect entirely through an app typically verify your bank account through Plaid rather than a signature at a counter. This site's comparison of online lending against storefront lending explains why online lenders lean harder on ACH and Plaid verification than a physical location does, since there's no teller across the counter to check anything in person.
Possible Finance's blog documents exactly where that verification chain runs into trouble for Chime: a Chime account can't be linked through Plaid to serve as a primary account, even though Chime is an FDIC-insured checking-type account, not a prepaid card. Some underwriting systems flag online-only banks the same way they flag prepaid debit products, whether or not that classification is technically accurate. Advance America excludes prepaid accounts by policy but hasn't published language confirming whether that exclusion extends to Chime specifically. Until a lender says so directly, the honest label for that gap is "unclear," not "confirmed."
What Lenders Check Before Approving You
Beyond the account-type question, payday lenders generally underwrite around two things, per the CFPB: an active bank account and proof of income, not a direct-deposit requirement specifically. That's the qualification baseline worth carrying into any application regardless of which bank issues your account, and it's what lenders actually check before approving you. The open question in every case above is whether a specific lender's Plaid integration or internal account-type list treats a Chime account as an active bank account.
That's also why a phone call beats a search result here. A lender's underwriting rules can differ from what any third-party article guesses about them, this one included, since none of these lenders' own pages settle the Chime question either way.
Availability Varies By State
Chime Instant Loans are available only to eligible Chime members in certain states, per Chime's own help page. Don't assume any lender here operates in your state, and payday lending itself is banned or effectively unavailable in a number of states: New York's usury caps make it effectively illegal there, as this site's own New York payday loan law article covers in detail. This site's own state-law coverage of New York, Illinois, Ohio, Mississippi, Texas, and Florida walks through what's legal where in more detail than a national comparison like this one can.
Nothing here should be read as confirming that any product is available where you live. State rules change the underlying legality of a payday loan; account-type policy changes whether a specific lender will fund you at all. Both questions matter, and this article only answers the second one. If you don't have any qualifying bank account at all, whether Chime or otherwise, that's a separate eligibility problem this site covers on its own.
Checking your state's legal status first is worth doing before you spend time on the account-type question at all: a lender that doesn't operate where you live can't fund you regardless of what its FAQ says about bank accounts. This site's state-by-state coverage is the faster place to start that check than a general search.
What To Do With This
Check SpotMe and MyPay in your Chime app before you apply anywhere else. Both are already tied to your account, and both cost less than the typical storefront payday loan, per the CFPB's 391% APR figure above. If you need more than SpotMe or MyPay cover, look at whether you qualify for Chime Instant Loans in your state before comparing outside lenders.
If you do move to a third-party lender, call their support line and ask the account-type question directly instead of trusting a blog post's list. "Do you accept Chime specifically, or just checking accounts generally" is a one-sentence question, and it's the one none of these lenders' public pages fully answer yet. Write down who you spoke to and what they said, since a phone rep's answer today is the closest thing to a real source until one of these lenders updates its FAQ.
Ask a second question while you have someone on the line: whether Chime can serve as the primary funding account or only as a repayment method, since Possible Finance's own blog draws exactly that line and other lenders may follow a similar internal rule without publishing it. A rep's answer to that specific phrasing will tell you more than another roundup article will.
Frequently Asked Questions
Do any payday lenders confirm they accept Chime?
No lender reviewed here has a public statement affirmatively confirming Chime acceptance by name. Possible Finance documents that Chime can only be a secondary payment method, not a primary account, and Advance America excludes prepaid-type accounts without naming Chime specifically.
Are payday loans with Chime cheaper than Chime's own SpotMe or MyPay?
Chime's own products cost less than the typical storefront payday loan you'd get through a third party. SpotMe charges no fee for $20 to $200 in coverage, and MyPay charges a 3% fee capped at $5. A typical storefront payday loan runs roughly 391% APR, per the CFPB's payday-loan explainer, far above Instant Loans' 35.99% cap.
Does Chime offer payday loans directly?
Chime doesn't market anything as a payday loan. It offers SpotMe overdraft coverage, MyPay, and Instant Loans, a product issued by The Bancorp Bank N.A. and serviced by Chime Capital LLC with a maximum 35.99% APR, structured differently from a flat-fee two-week payday loan.
Why would a lender reject a Chime account?
Some lenders' underwriting systems flag online-only bank accounts similarly to prepaid cards, even though Chime is an FDIC-insured checking-type account. Possible Finance's blog documents one concrete case: Chime can't be linked through Plaid as a primary account. Advance America excludes prepaid accounts by policy without naming Chime.
Is Chime Instant Loans available in every state?
Chime's own help page states that Instant Loans are available only to eligible Chime members in certain states. That state-by-state limit applies on top of the deposit and account requirements, so meeting the qualifying-deposit threshold doesn't guarantee the product is offered where you live; check eligibility with Chime.
Where can I check whether a payday loan is even legal in my state?
Chime and account-type policy are only half the question. This site's own state-by-state coverage of New York, Illinois, Ohio, Mississippi, Texas, and Florida walks through where payday lending is restricted, capped, or effectively unavailable, which matters before any lender's Chime policy becomes relevant at all.